
 Frontline Legacy Group
Built by first responders.
First home.Next mission.
A first-time homebuyer guide built for first responders and military. Understand your financing, overtime income, Ohio assistance, and every step from your first question to your first set of keys.
No upfront review fee. No purchase obligation.
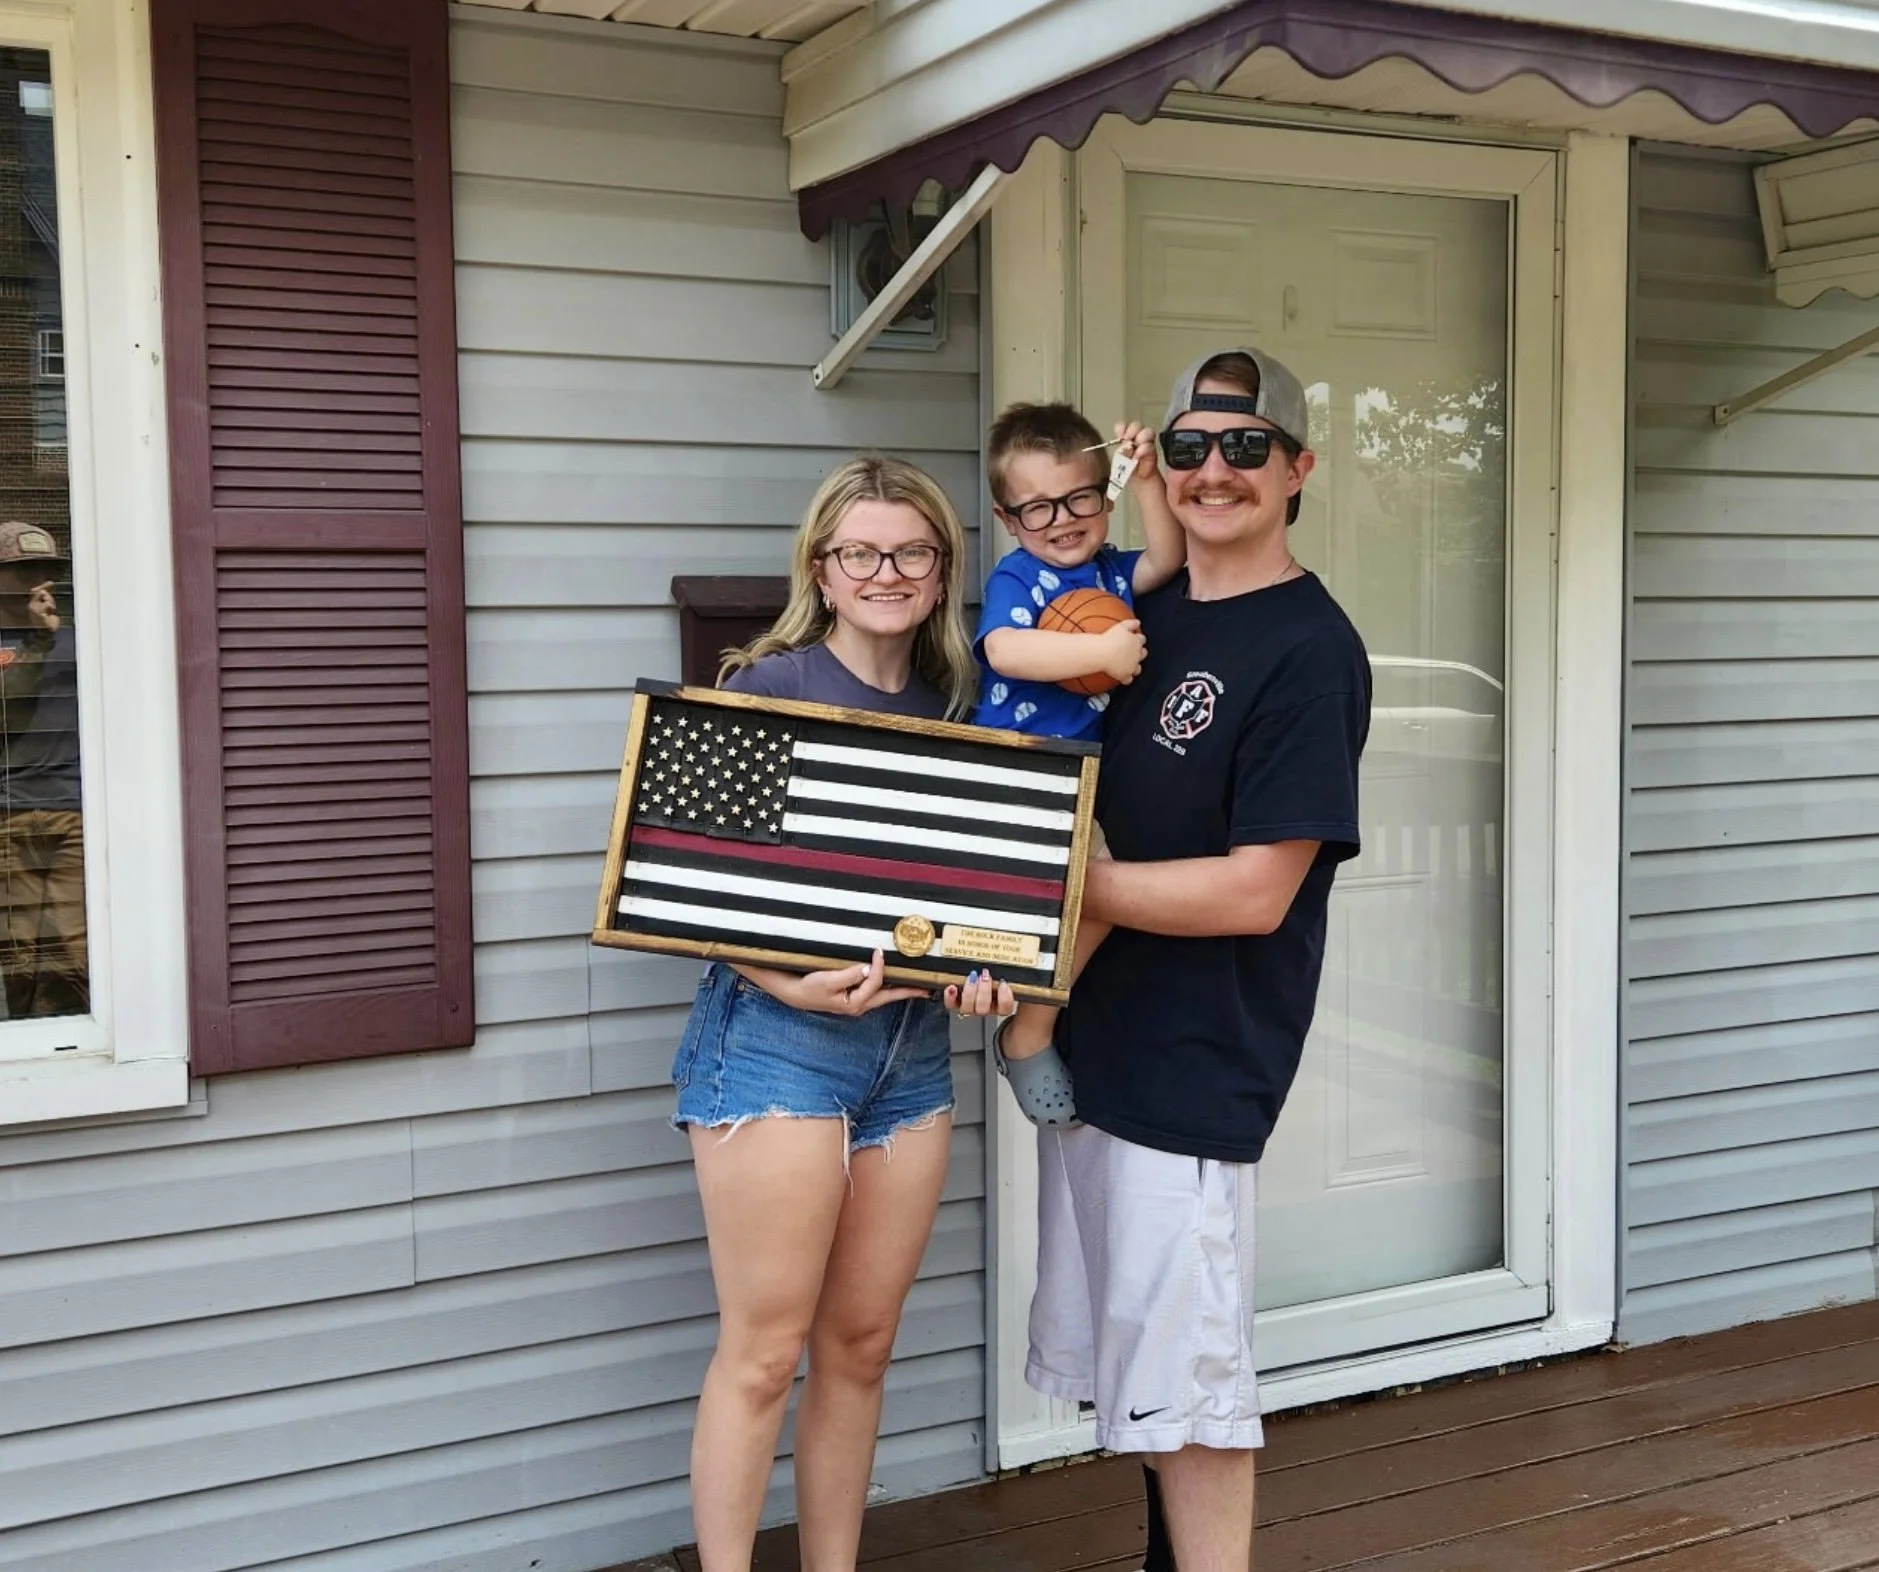 Real Frontline buyers / First home
Frontline's published impact totals. Individual savings and benefits vary.
Run the numbers.
Then build the plan.
Explore what a potential 1% rebate could mean for your purchase before you start shopping. The number is a starting point, not an offer, approval, or guaranteed amount received.
See what 1% could mean.
Example: a $400,000 home × 1% = $4,000.
Illustration only, before eligibility review. Enter a price from $100,000 to $1,000,000. This is not a mortgage approval, cash-to-close estimate, or guaranteed cash payment.
Start with facts.
Build from there.
You do not need every answer before you begin. A lender review helps turn your income, savings, credit, and timeline into a realistic starting point.
What feels comfortable?
Include principal, interest, taxes, insurance, applicable HOA fees, utilities, and maintenance. Your approval ceiling does not have to be your spending target.
What do I need up front?
Plan for down payment, closing costs, prepaid items, inspections, and reserves. Earnest money is generally credited toward your closing funds.
Can my overtime count?
It may. Overtime, shift differential, and extra-duty pay need lender review. Bring documentation of your pay history and every source of income.
Where do I stand?
A perfect score is not a universal requirement. Your credit, debts, income, savings, loan program, and lender standards are evaluated together.
You may not need 20% down.
Some loans allow lower down payments; certain eligible borrowers may qualify for no-down-payment options. Compare the full payment, mortgage insurance, and cash needed before choosing.
Your lender conversation checklist
- Recent paystubs, W-2s, and employment information.
- Overtime, shift, specialty-pay, and second-job history.
- Bank statements, savings, and current debt payments.
- Your comfortable payment and planned move date.
- Military eligibility documents, if applicable.
Your lender will specify the documents and history needed. Pre-approval is conditional and is not final loan approval.
Four phases.
One clear next step.
Use the roadmap to see where you are and what comes next. Some steps overlap; your contract and lender determine the timing.
Prepare
Clarity before the first showing.
- 01Buyer consultation
Define your goals, move date, locations, and comfortable payment.
- 02Lender conversation
Review income, assets, debt, credit, and available loan options.
- 03Pre-approval
Review the payment, estimated cash-to-close, and conditions of your pre-approval.
- 04Buyer representation
Understand your agent agreement, services, scope, and compensation before touring together.
- 05Search strategy
Build your search around budget, commute, needs, and life between shifts.
Pursue
Shop with a purpose and a plan.
- 06Focused home search
Watch the homes that fit your priorities and financing.
- 07Home tours
Look beyond finishes at layout, systems, condition, location, and ownership costs.
- 08Property analysis
Review comparable sales, taxes, disclosures, and the competition.
- 09Offer strategy
Weigh price, financing, timing, and contractual protections together.
- 10Negotiation + acceptance
Understand the terms and deadlines before the agreement becomes binding.
Protect
Know the home. Protect the purchase.
- 11Earnest money + loan file
Meet your deposit deadline and provide lender documents promptly.
- 12Inspection + due diligence
Use qualified professionals and review available responses within your contract deadlines.
- 13Title + insurance
Review title issues, homeowners insurance, and HOA or condo requirements, if applicable.
- 14Appraisal
The lender evaluates property value when required; discuss any value gap before proceeding.
- 15Underwriting
Respond to conditions. Check with your lender before taking new debt or making major financial changes.
Close
Confirm the details. Prepare for ownership.
- 16Closing Disclosure + final figures
Review your loan terms, charges, and cash needed. Resolve differences with your lender and closing agent.
- 17Final walkthrough
Confirm the home’s condition and agreed items before closing.
- 18Closing + possession
Sign, fund, and receive possession according to the contract and local process.
- 19Your first year
Set up utilities, know your warranty terms, plan maintenance, and keep your Frontline team in reach.
For most purchase mortgages, review your Closing Disclosure at least three business days before closing. Ask your lender about the timing and resolve discrepancies before signing.
CFPB closing checklist ↗Know who is
in your corner.
Under NAR's settlement-related MLS practice changes, an MLS Participant working with a buyer needs a written agreement before touring together, in person or live virtually.
Read NAR's consumer guide ↗Simply asking an agent about services or visiting an open house on your own does not require that agreement under this practice change. State, local, MLS, and brokerage requirements also apply.
- 01Services and representation
Understand who represents you, what they will do, and how you will communicate around your shifts.
- 02Scope, duration, and exit terms
Review the area or properties covered, any exclusivity, the agreement's length, and how changes or termination work.
- 03Compensation and your responsibility
Compensation is negotiable. Understand the agreed amount and what you may owe if seller-paid compensation does not cover it.
Your first conversation can be about understanding your options. Review the written agreement with your agent before committing.
Your service.
Your buyer edge.
Eligible first responders and military buyers may receive a 1% rebate on qualifying home purchases with Frontline, along with other participating-provider benefits.
Built for the family behind the uniform.
Frontline Buyer Edge combines first-responder-focused guidance, a potential buyer rebate, select partner incentives, and qualifying after-closing benefits. These are buyer benefits—not selling incentives.
1-year home warranty*
Complimentary coverage for qualifying buyers after closing. Provider terms, covered items, exclusions, and service fees apply.
LODD mortgage protection*
Ask about up to $525,000 in line-of-duty mortgage protection for qualifying borrowers through participating lending relationships.
Watch Jared + Shyan explain it ↗A team that gets the job.
Guidance around overtime, shift schedules, and family commitments, plus a review of potential lender, title, and partner benefits.
*Benefits depend on written program terms, brokerage approval, lender/provider participation, transaction limits, applicable rules, and eligibility. Rebate and other savings are not automatically additional or stackable. Confirm current written LODD availability, coverage, and exclusions with the provider before relying on the benefit. Buyers may choose their lender and other service providers.
Not all hero programs
start with the same rebate.
Before you choose a real estate partner, compare the published base real estate incentive with the full set of benefits, costs, eligibility requirements and the professionals who will guide your purchase.
Homes for Heroes publicly describes a 0.7% Hero Rewards real estate check after closing. Frontline advertises a potential 1% buyer rebate on qualifying purchases. Both amounts are estimates, not guaranteed net cash.
base percentages
Illustrative percentage comparison only (1% vs 0.7%). It is not a full comparison of total program savings. Homes for Heroes may offer additional mortgage, title or partner savings. Frontline benefits likewise depend on individual provider and transaction terms.
Homes for Heroes states Hero Rewards are sent after closing; Frontline's buyer rebate may be applied at closing where permitted. Actual amounts and treatment may differ due to financing, brokerage, commission and eligibility restrictions. Neither outcome is a cash-in-hand guarantee.
Published program descriptions reviewed October 25, 2026. Homes for Heroes is a separate company and is not affiliated with Frontline Legacy Group.
Trust is earned.
Not invented.
First-time buyers need more than advertising: they need a team that follows through, communicates clearly, and understands what homeownership means to their family.
“Jared was incredibly professional, hard working and always kept us informed.”
Client testimonial published on Frontline Legacy Group's homepage. Not represented as a first-time buyer review.
See published client feedback ↗Real first homes.
The real family featured at the top of this guide purchased their first home with Frontline. Explore Buyer Edge to see more families and the program behind their experience.
Explore real buyer stories ↗Bring your questions.
Report to Roll Call.
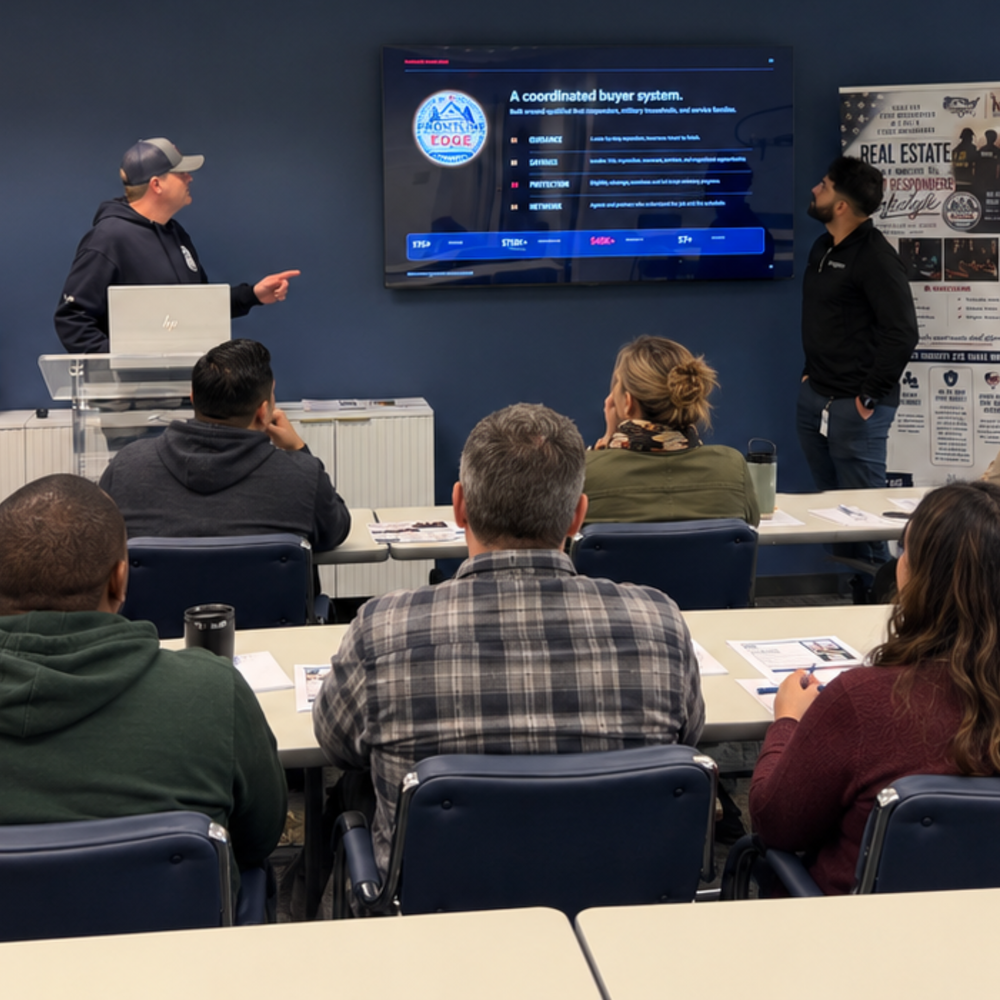
Not ready to buy yet? Join Jared Lee and Shyan Manteghi for a live homebuyer briefing. Ask about overtime, financing, down payments, and what your next move could look like.
No pre-approval needed. Come with one question.
1st + 3rd Wednesdays: 11 AM–12 PM ET
2nd + 4th Wednesdays: 6–7 PM ET
Build your
first-home plan.
Use the existing secure Buyer Edge two-step inquiry to start your conversation with Frontline. Your form will submit using the current Buyer Edge process—not a new or untested form endpoint.
To prevent lost inquiries, this page does not attempt to submit or store personal information itself. Opening the form below loads Frontline's existing Buyer Edge page at its form anchor. If the embedded form does not display correctly, use the direct link above.
Good questions.
Better decisions.
Your financing and contract are specific to you. Use these answers to prepare for the conversation.
Talk to Frontline: 330-621-8918 ↗Do I need 20% down?
No. Down-payment requirements vary by loan type, lender, and borrower eligibility. Some eligible borrowers may qualify for lower or no-down-payment options. Compare mortgage insurance, total payment, and other loan costs.
Can overtime or shift pay help me qualify?
It may. Lenders review the history, consistency, documentation, and expected continuation of income under the applicable loan rules. Have a licensed lender review your actual pay records before relying on overtime in your budget.
How much cash will I need?
Ask for a personalized estimate covering down payment, closing costs, prepaid items, inspections, and reserves. Credits or assistance may reduce eligible costs. Earnest money is generally credited at closing; it is not automatically an extra fee on top of your final cash requirement.
Is pre-approval a final loan approval?
No. Pre-approval helps establish a lender-reviewed buying position, but final approval depends on underwriting, the property, required documents, and any conditions. Keep your finances stable and discuss changes with your lender.
Is the 1% rebate guaranteed?
No. The illustrative 1% rebate is subject to written program terms, brokerage approval, transaction structure, lender limits, applicable rules, and eligibility. Ask Frontline to review your specific purchase. Other incentives are not automatically additive.
Do I have to use a preferred lender?
No. Buyers may choose their lender and other service providers, subject to applicable transaction requirements. Some partner benefits require a participating provider. Review those requirements before selecting services.
How does Frontline compare with Homes for Heroes?
Homes for Heroes publicly advertises a 0.7% base real estate Hero Reward after closing. Frontline advertises a potential 1% buyer rebate on qualifying purchases. On a $400,000 purchase, those illustrative base amounts are $2,800 and $4,000, respectively. Compare the full package, not just base percentages: both programs have additional terms and possible partner savings.
What is the Ohio Heroes mortgage program?
Ohio Housing Finance Agency's Ohio Heroes program offers discounted mortgage rates to eligible public-service professionals, including firefighters, EMTs, paramedics, law enforcement officers and eligible military participants. A participating lender can review whether you qualify and whether optional OHFA down-payment assistance fits your financing.
Official Ohio Heroes program ↗How long does buying a first home take?
Preparation may take days or months, depending on your circumstances. The home search depends on inventory and your priorities. After acceptance, your contract, lender, title work, and other transaction requirements determine the timeline.
What if I am not ready to buy yet?
You can start with the free Roll Call homebuyer briefing or ask Frontline about your starting point. Exploring your options does not require a purchase commitment. Your next step may be saving, organizing documents, improving credit, or simply learning more.
You handle the shift.
Let's plan the move.
Start with our short Buyer Edge inquiry. A Frontline agent can help you understand your starting point, potential benefits, and next step.
No upfront review fee. No purchase obligation.
Your inquiry does not guarantee financing or program eligibility.